
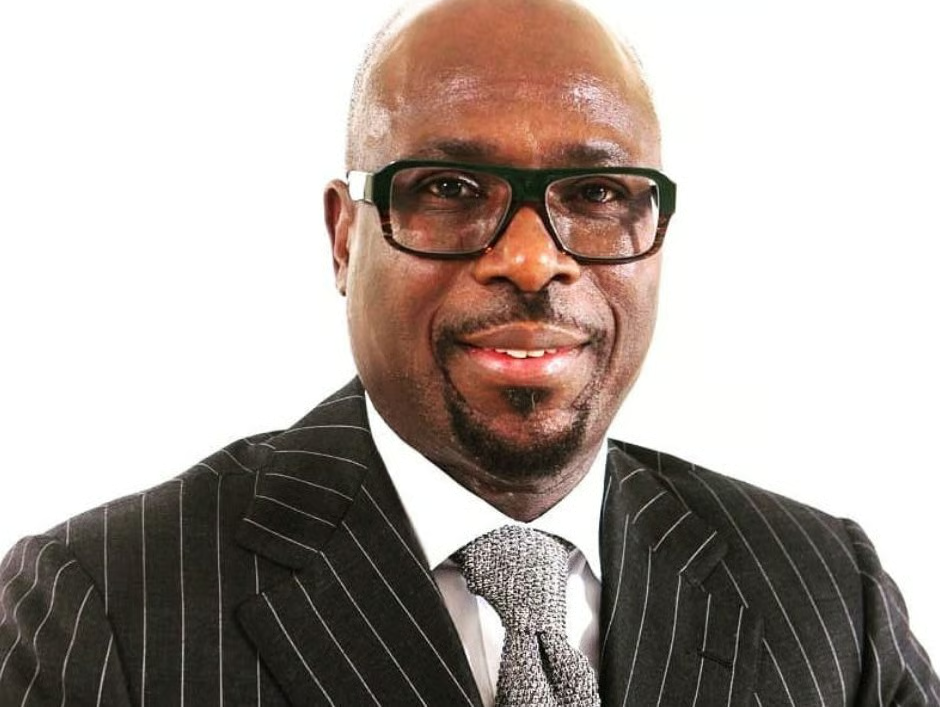
T1 Marine Services, the marine logistics company owned by billionaire Tunde Folawiyo, is engaged in a protracted eight-year legal struggle with the Federal Inland Revenue Service (FIRS) over disputed tax liabilities.
The dispute centres on ₦1.65bn in tax assessments and ₦2.88bn in business expenses that the tax authority has disallowed, bringing the total contested figure to over ₦4.5bn.
The conflict highlights a recurring tension between major Nigerian corporate entities and the Federal Inland Revenue Service over the interpretation of deductible business expenditures.
At the heart of the disagreement are the “disallowed expenses,” a common point of friction in Nigerian corporate tax audits. Under the Companies Income Tax Act, businesses can only deduct expenses that are incurred wholly, exclusively, and necessarily for the purpose of producing their actual profits.
The FIRS has reportedly rejected ₦2.88bn of T1 Marine’s claimed operational costs, arguing they do not meet these strict criteria. This rejection effectively increases the company’s taxable income, leading to the additional ₦1.65bn tax demand.
T1 Marine provides critical support services to the Nigerian oil and gas industry, managing the complex logistics required for offshore operations. The company’s role is central to the value chain of energy production in the Gulf of Guinea.
Tunde Folawiyo, a veteran of the Nigerian financial and industrial landscape, has built a diversified portfolio across banking and energy. The longevity of this legal battle, spanning nearly a decade, suggests a deep disagreement over accounting treatments and regulatory interpretations.
Tax Assessment Disputes and Marine Logistics
The case arrives at a time when the FIRS is under significant pressure to increase non-oil revenue for the Nigerian government. This has led to more aggressive auditing of high-turnover companies across the energy and logistics sectors.
Industry analysts note that protracted tax disputes can create financial uncertainty for companies, affecting their ability to plan long-term capital investments in expensive marine assets.
The marine logistics sector is particularly susceptible to these disputes due to the high cost of equipment maintenance and the complexity of cross-border service contracts, which often lead to disagreements over what constitutes a valid business expense.
The use of the Tax Appeal Tribunal (TAT) is the standard first step for companies contesting FIRS assessments before cases migrate to the Federal High Court. The eight-year timeline for this specific dispute reflects the typical bottlenecks found in Nigeria’s tax adjudication process.
The outcome of the T1 Marine case is expected to provide further clarity on how the Nigerian courts interpret the necessity of operational expenses within the specialized marine services sector.
A ruling in favour of the company would protect the ability of marine operators to deduct significant operational overheads. Conversely, a victory for the FIRS would signal a tightening of the rules regarding what the state considers a legitimate business cost.
T1 Marine has not issued a recent public statement regarding the current status of the litigation. The matter remains pending as the parties seek a legal resolution to the multi-billion naira claim.
Explore more Companies stories and analysis from Business Elites Africa.


