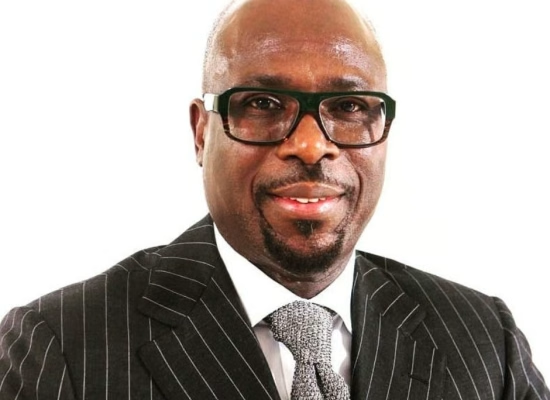
T1 Marine Services, a company chaired by prominent Nigerian industrialist Tunde Folawiyo, is contesting a tax demand totaling ₦1.65 billion.
The dispute relates to tax assessments made on the company’s accounts for the financial years spanning 2014 to 2016. The company is challenging the validity and basis of the demand, which approximates $1.2 million based on prevailing assessments.
The disagreement comes as Nigerian tax authorities intensify efforts to recover unpaid revenues from corporate entities across the energy and maritime sectors. T1 Marine provides critical support services to the Nigerian oil and gas industry, operating in a high-capital environment where tax compliance and accounting interpretations often lead to protracted disputes.
Tunde Folawiyo, the chairman of T1 Marine, is one of Nigeria’s most established businessmen with diverse interests in investment, energy, and finance. His companies have long been integrated into the nation’s industrial landscape, making the resolution of this tax matter a point of interest for observers of corporate governance and regulatory compliance in Nigeria.
The company is expected to present its case before the relevant tax adjudication bodies to resolve the discrepancy between its filed returns and the assessments issued by the tax authority.
Tax Assessment and Legal Recourse in Nigeria
Tax disputes of this scale are not uncommon in Nigeria, particularly for companies operating in the extractive and maritime industries. Such cases typically originate from differences in how the Federal Inland Revenue Service (FIRS) and corporate taxpayers interpret taxable income, allowable expenses, and applicable tax credits.
When a company disagrees with an assessment, the standard procedure involves an objection filed with the taxing authority. If a resolution cannot be reached administratively, the matter is typically escalated to the Tax Appeal Tribunal (TAT), an independent quasi-judicial body designed to resolve tax disputes without the lengthy delays associated with the regular court system.
The 2014 to 2016 period in question was characterized by significant volatility in the oil and gas sector due to fluctuating global crude prices, which impacted the operational costs and revenue reporting of many marine service providers. It is common for tax authorities to revisit accounts from this era as part of wider audit cycles to ensure all liabilities were accurately declared.
For T1 Marine, the outcome of this dispute will depend on the company’s ability to provide documentary evidence that contradicts the tax authority’s findings. The company’s legal and financial teams will likely focus on proving that the ₦1.65 billion demand is either an overestimation or based on an incorrect application of tax laws applicable during those financial years.
Beyond the immediate financial implication, the case reflects the broader tension between the Nigerian government’s drive to increase non-oil revenue and the private sector’s demand for fair and predictable tax administration. The FIRS has consistently pushed for more aggressive tax collection to bridge the federal budget deficit, leading to a rise in audits of high-net-worth individuals and their associated companies.
The resolution of the T1 Marine case will likely hinge on a detailed reconciliation of the 2014-2016 ledger. The next stage of the process will involve formal hearings where the company’s auditors and the tax authority’s representatives will argue the merits of the assessment before the tribunal.
Explore more Companies stories and analysis from Business Elites Africa.